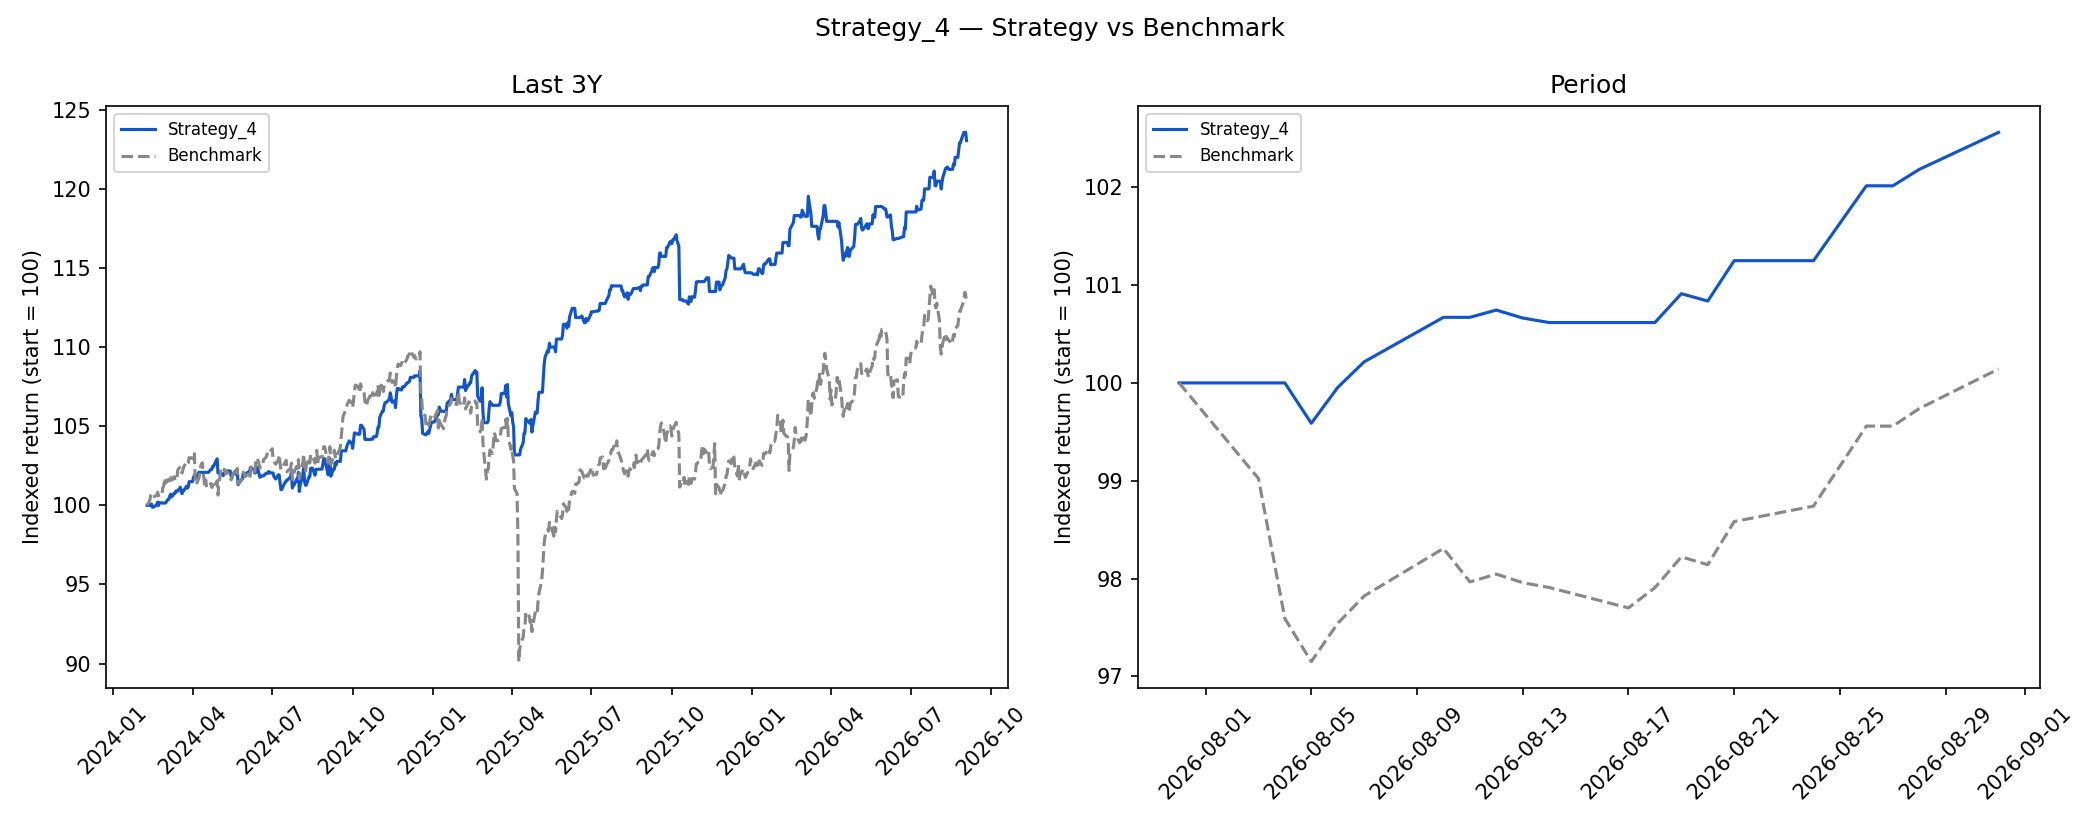
Predictive Gamma: August 2026
The Predictive Gamma strategy returned +1.30% in August against a benchmark return of just +0.14%, delivering +1.16% of outperformance as the ML classifier captured the month's frequent volatility-crush sessions while filtering out the high-uncertainty Jackson Hole event that cost the undiscriminating straddle seller dearly. The margin over benchmark is the clearest monthly illustration yet of the strategy's stated edge: not the return earned on days it trades, but the losses avoided on the days it doesn't.
The Predictive Gamma strategy returned +1.30% in August against a benchmark — selling a 0DTE S&P 500 straddle every session — that returned just +0.14%, delivering +1.16% of outperformance. The result is a direct expression of the strategy's core proposition: the ML classifier's value lies not in the return earned on days it trades, but in the sessions it correctly identifies as low-conviction and skips. August contained both the ideal backdrop for the strategy's short-straddle signal — the VIX near 14 for most of the month, with realised moves consistently smaller than implied, producing steady volatility-crush sessions — and at least one session that would have been highly damaging to an undiscriminating seller: the Jackson Hole address on 29 August, which drove an outsized intraday move as Warsh's hawkish remarks pushed September rate-hike odds from 36% to 67%.
A naive straddle seller would have been fully exposed to that move; the classifier, ingesting VIX/VIX1D ratios, VVIX momentum, and realised-versus-implied spreads, is designed precisely to flag elevated-uncertainty sessions and stand aside. The +1.16% margin over benchmark in a month that included a genuine macro surprise is the clearest available read on the model's filtering value.
Talking points
- The strategy earned more than eight times the return of its benchmark in August — not by trading more, but by being selective about when to trade. Most of the month's sessions offered a clean volatility-crush environment with the VIX near its 2026 lows; the classifier engaged on those days and collected premium efficiently. The benchmark, which sold every session indiscriminately, gave much of that back on the days that didn't fit the profile.
- The Jackson Hole session on 29 August was the clearest test of the strategy's filtering discipline in the month. Fed Chair Warsh's hawkish remarks drove an unusually large intraday move — exactly the scenario a short straddle seller does not want to be exposed to. The model's design is to issue a Flat signal on days where the probability of a volatility breakout is elevated; a +1.16% margin over a benchmark that absorbed that session in full is evidence the filter worked as intended.
- Clients should remember that outperforming a high-risk benchmark is not the same as low risk. The 0DTE straddle — even when filtered by the model — carries extreme intraday gamma exposure, and a single large move on a day the model trades can produce a loss that exceeds many sessions of accumulated premium. August's +1.30% return reflects a month where the model's edge was real and the macro surprises were absorbed; that combination will not repeat identically every month.