Market update: August 2026
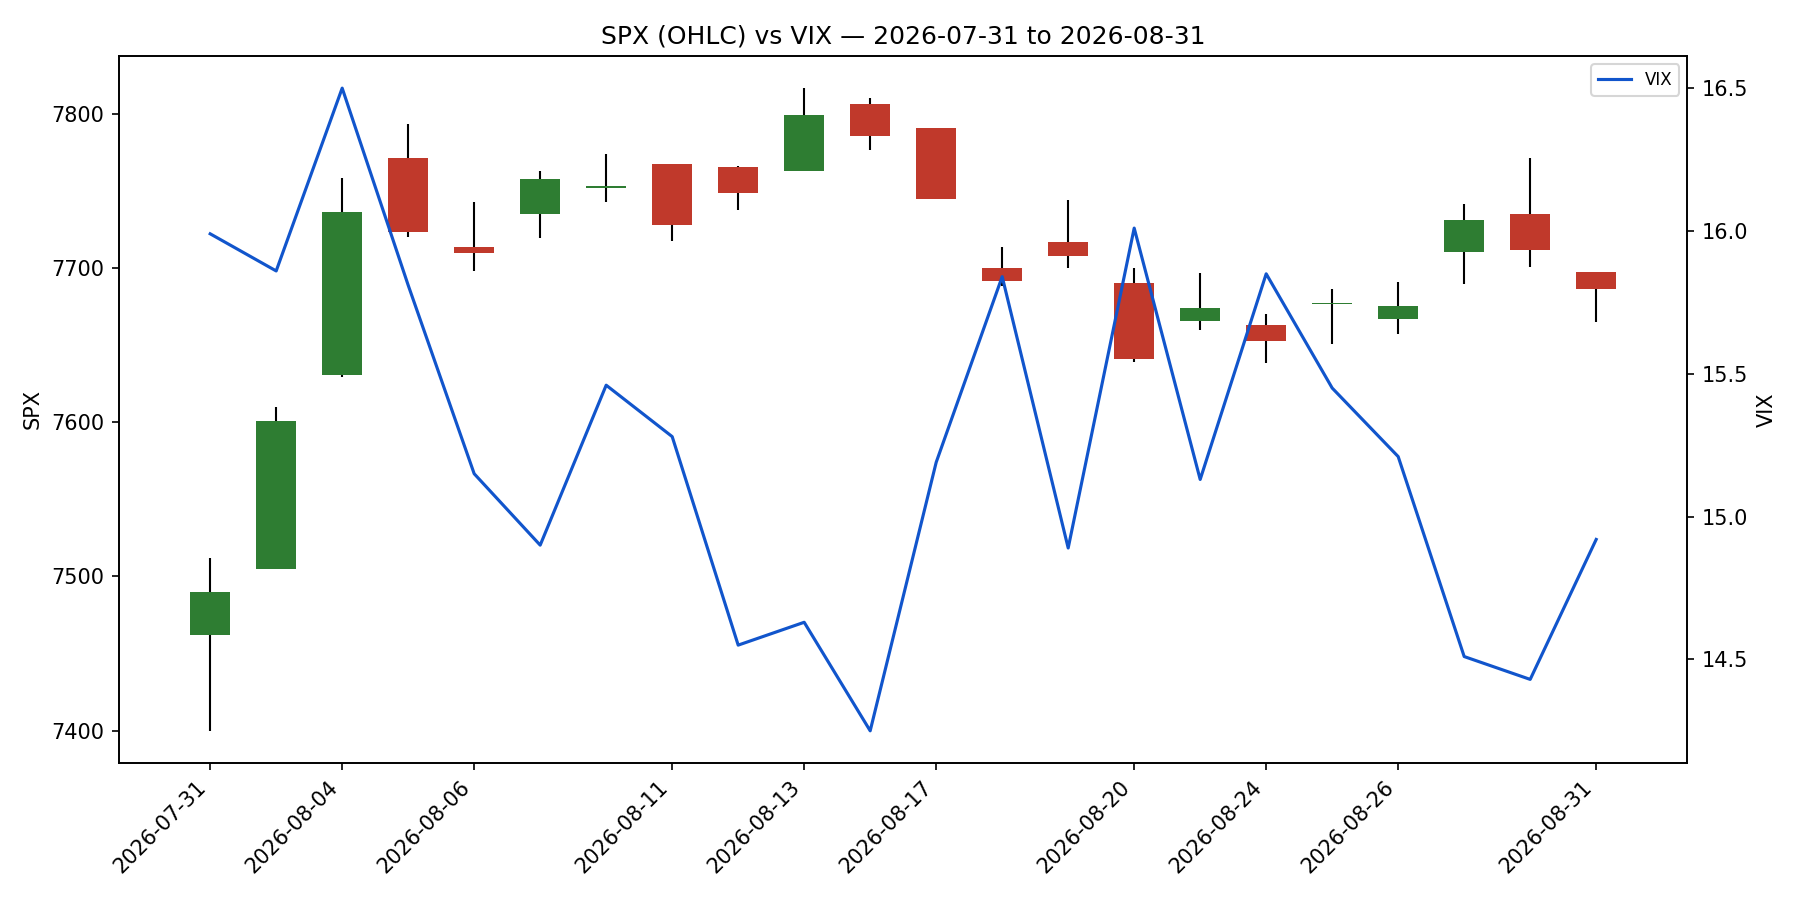
The dominant driver of August 2026 was Fed Chair Kevin Warsh's Jackson Hole address on 29 August, which reaffirmed the 2% inflation target, pushed September rate-hike probabilities from 36% to 67%, and drove the 10-year UST yield to 4.77% (a 19-month high), with the 30-year touching 5.34%, its highest level since 2007. Against that backdrop, US equities proved resilient: the S&P 500 gained c. +2.7% and the Nasdaq-100 +4.2%, their best August performance since 2021, with software and hyperscaler names leading after a sharp recovery from spring lows.
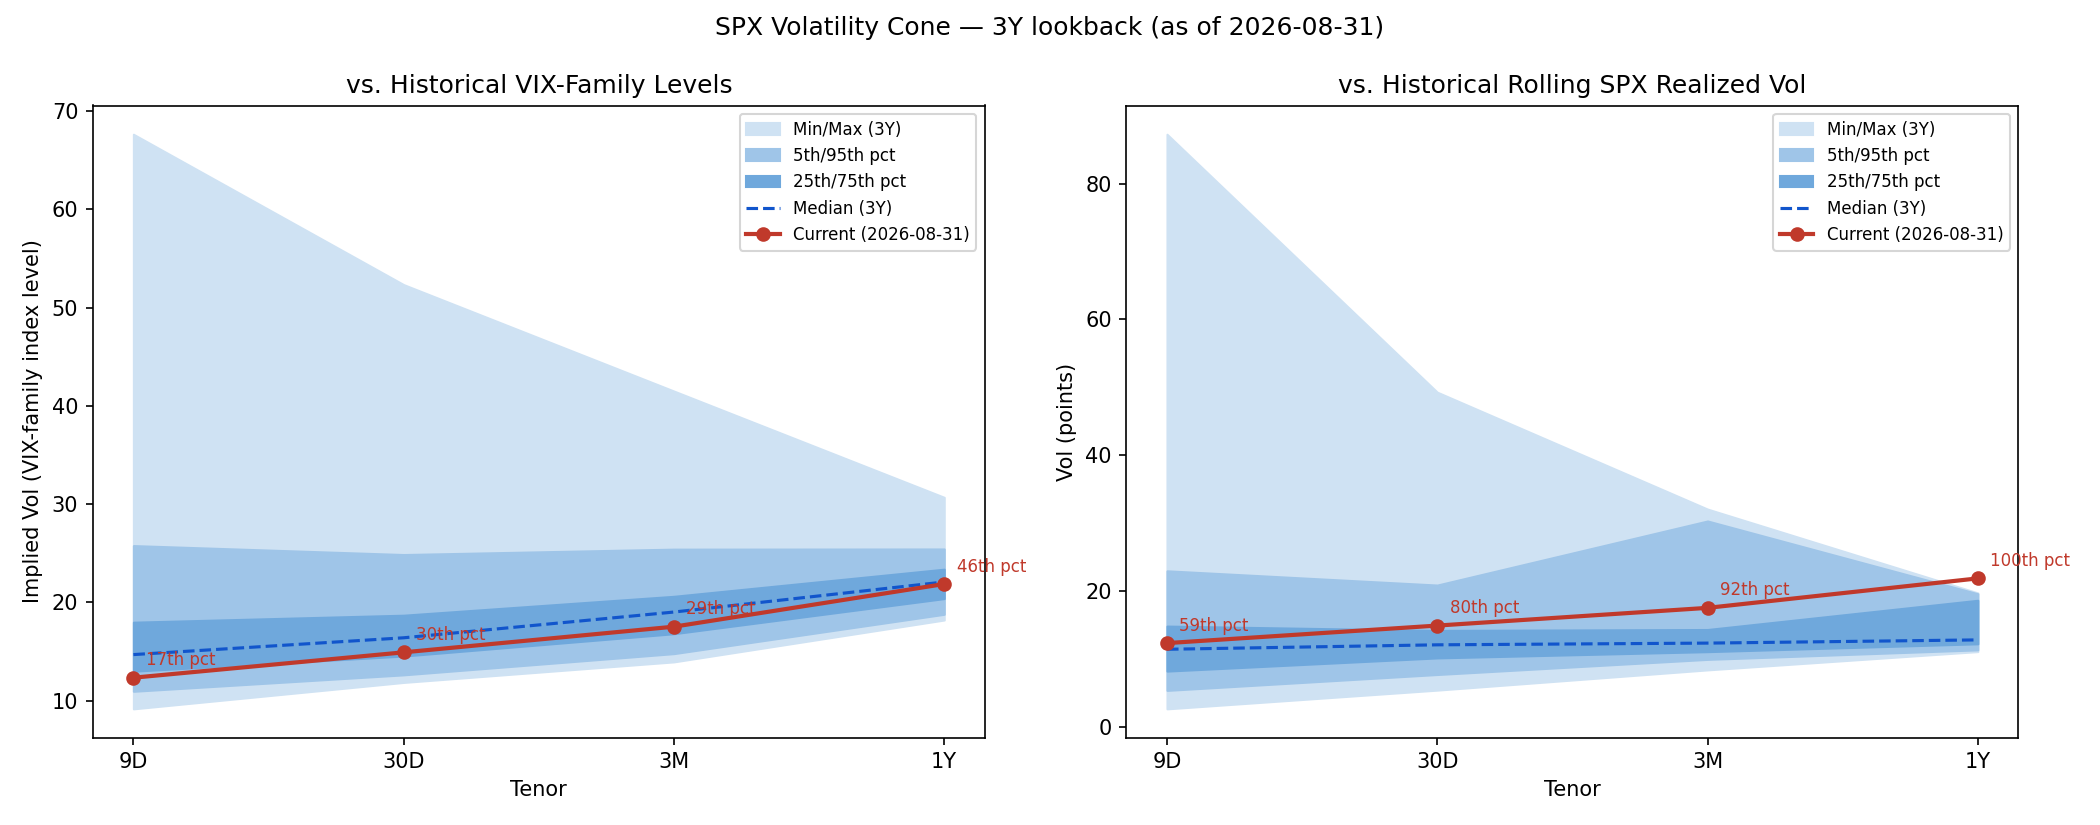
European equities were a comparative laggard, the Stoxx 600 ending the month roughly +0.9% higher and the Euro Stoxx 50 closing near 6,370 — reflecting the more acute drag of rising long-end yields globally, with 10-year rates in Germany, France, and the UK pressing multi-year highs. The VIX fell to 14.13 intraday, its lowest level of 2026, before the Jackson Hole shock lifted it to close August at 14.92 — a regime that kept implied volatility compressed and the VRP thin for most of the month.
Gold closed out August at approximately $4,432/oz, up roughly 9.5% on the month, as the debasement trade resurfaced amid fiscal deficit concerns. Brent crude finished back above $90, with WTI settling near $86, after renewed Strait of Hormuz hostilities in the final days of August reversed the energy calm that had characterised much of the summer. EUR/USD ended the month near 1.1590, weighed by the widening US rate premium following Warsh's remarks.